LoginSign Up

Casey Allen

Founder at Enterprise Rising
253K insights
Visible to Casey
Casey won't be able to see or reply to your conversation in incognito mode
Ask about me
Learn from my insights
Jam on a problem
NOTE: If you request to connect, please also include a note about where & when we've met or I may accidently ignore your invite. If we've never met then let's work on that first. I'm a very easy person to get an email in...
Minneapolis, Minnesota
Casey Allen
View on LinkedIn
Casey Allen

Jason ✨👾SaaStr.Ai✨ Lemkin

@jasonlk

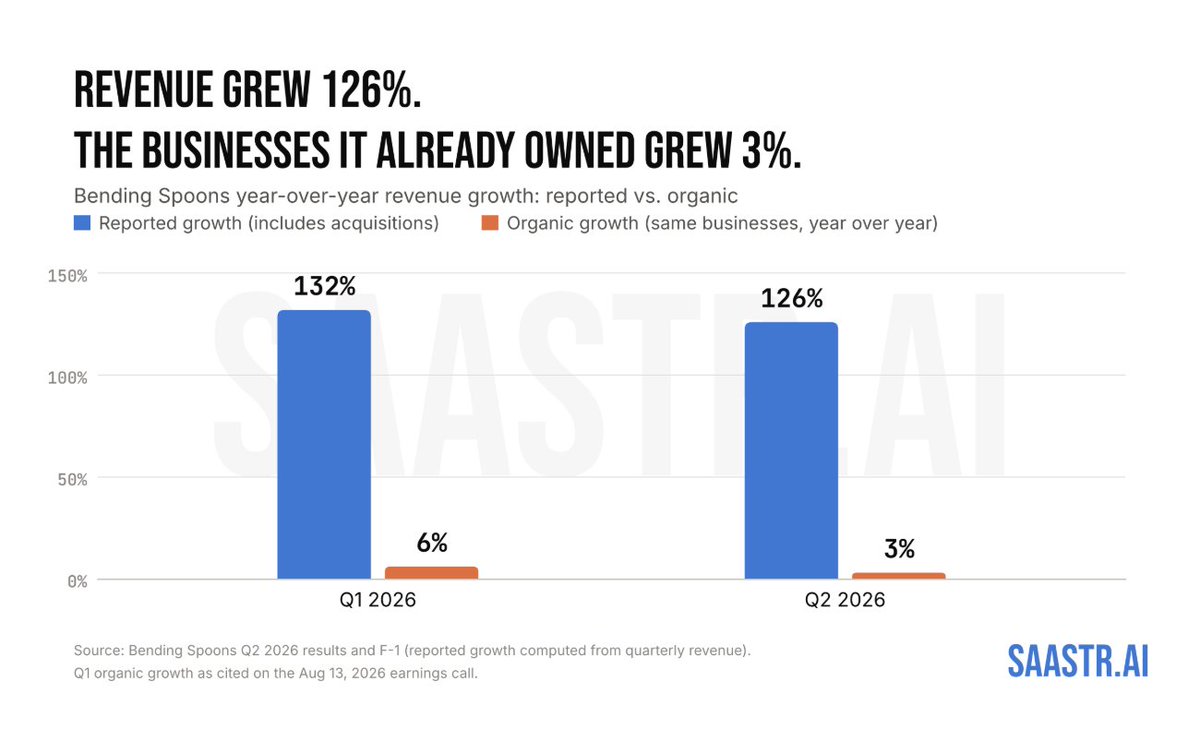
Bending Spoons is worth $24 billion. It trades at 8x ARR and buys B2B companies at 2.3x to 2.7x ARR. 5 learnings from its first 102 days as a public company: #1. Revenue grew 126%. Organic growth was 3%. Nearly all of the $393M of added revenue in Q2 came from six acquisitions. The CEO says he doesn't optimize for organic growth. He optimizes for EPS, which grew 167%. #2. R&D is 8% of revenue. Sales and marketing is 10%. HubSpot and Datadog each spend about 70% of revenue on those two lines. Bending Spoons spends 18.6%. About 60 people run Vimeo. The core team is under 700 people, at $4M+ of revenue each. #3. Miro sold at 2.3x ARR, five weeks after Airtable at 2.7x. $1.08B of ARR for $2.64B, signed 37 days apart. Miro was valued at $17.5B in 2022. Bending Spoons underwrites to a 25% unlevered return. At its 54% margin, that supports about 2.2x ARR. #4. 1,830 people came with AOL, Eventbrite and Vimeo. Only a few hundred were kept. Airtable arrived with 935 employees, more than Bending Spoons’ entire core team. Reorganization costs were $51M in Q2 alone. #5. AI writes 90%+ of the code. Customers pay about 10% more for the AI features. The CEO says a customer who paid 100 will now pay about 110. The AI gain shows up as capacity: the same 60 people on a business four times the size. If you're at $300M to $800M in ARR growing under 25%, this is the buyer most likely to at least call. But ... the only do a handful of deals a year. Its own stock trades at roughly 7x to 8x revenue. Your revenue is worth about 3x more inside Bending Spoons than it is in your hands.
Bending Spoons is worth $24 billion.

It trades at 8x ARR and buys B2B companies at 2.3x to 2.7x ARR.

5 learnings from its first 102 days as a public company:

#1. Revenue grew 126%. Organic growth was 3%.

Nearly all of the $393M of added revenue in Q2 came from six acquisitions. The CEO says he doesn't optimize for organic growth. He optimizes for EPS, which grew 167%.

#2. R&D is 8% of revenue. Sales and marketing is 10%.

HubSpot and Datadog each spend about 70% of revenue on those two lines. Bending Spoons spends 18.6%. About 60 people run Vimeo. The core team is under 700 people, at $4M+ of revenue each.

#3. Miro sold at 2.3x ARR, five weeks after Airtable at 2.7x.

$1.08B of ARR for $2.64B, signed 37 days apart. Miro was valued at $17.5B in 2022. Bending Spoons underwrites to a 25% unlevered return. At its 54% margin, that supports about 2.2x ARR.

#4. 1,830 people came with AOL, Eventbrite and Vimeo. Only a few hundred were kept.

Airtable arrived with 935 employees, more than Bending Spoons’ entire core team. Reorganization costs were $51M in Q2 alone.

#5. AI writes 90%+ of the code. Customers pay about 10% more for the AI features.

The CEO says a customer who paid 100 will now pay about 110. The AI gain shows up as capacity: the same 60 people on a business four times the size.

If you're at $300M to $800M in ARR growing under 25%, this is the buyer most likely to at least call.  But ... the only do a handful of deals a year.

Its own stock trades at roughly 7x to 8x revenue. Your revenue is worth about 3x more inside Bending Spoons than it is in your hands.
View on 𝕏
Casey Allen

Minne Inno

@MinneInnovation

A real estate deal that would have set the stage for the first new office tower in downtown Albany in more than two decades has fallen apart. https://www.bizjournals.com/albany/news/2026/10/07/albany-office-tower-first-columbia-pioneer.html?csrc=6398&taid=6acba0efe3cb670001f77890&utm_campaign=trueanthem&utm_medium=social&utm_source=twitter

A real estate deal that would have set the stage for the first new office tower in downtown Albany in more than two decades has fallen apart. https://www.bizjournals.com/albany/news/2026/10/07/albany-office-tower-first-columbia-pioneer.html?csrc=6398&taid=6acba0efe3cb670001f77890&utm_campaign=trueanthem&utm_medium=social&utm_source=twitter
View on 𝕏
Casey Allen

Austen Allred

@Austen

It seems like this was bound to happen eventually. The standard practice in Silicon Valley has become that so many people have so many pro rata rights that it’s hard to bring in new money without early investors agreeing to waive pro rata they negotiated a legal right to. Some do, some don’t. Exercising pro rata in winners is where the highest risk investments really pay off, and sometimes it can make or break an entire fund. Pretty fundamental misalignment of incentives. I don’t know what the answer is.

View on 𝕏
Casey Allen
View on LinkedIn
Get the App
New to SuperMe?

Sign up free to work on your questions with people who've been there, like Casey.Download SuperMe for the best experience